
Base case
Your current inputs
1.25DSCR
- Monthly rent
- $2,500.00
- Monthly PITIA
- $1,998.23
- Rent minus PITIA
- $501.77
1.00 DSCR means rent equals PITIA.
Free DSCR estimate · no account required
Compare your base case with lower rent and higher taxes or insurance. Download the numbers free. Educational estimates—not an approval or rate quote.
Already own a rental? Estimate cash-out proceeds →Example result · edit the inputs before relying on this screen
Estimated rent is at least 1.25× PITIA at these inputs; provider underwriting still applies.
What property are these numbers for?
One tap — we don't ask for anything else.
*Excludes vacancy, maintenance, management, utilities, and other operating expenses.
Get your numbers and next-step questions by email. Phone optional. DSCRDealCheck reviews your request before any lender introduction.
Edit the example and select a state to create a share link.
Free scenario comparison
Change the calculator inputs above to update all three cases. Each stress starts from the base case; the two stresses are not combined. Loan amount, rate, term and HOA stay fixed.
Illustrative example — synthetic figures
Your current inputs
1.25DSCR
1.00 DSCR means rent equals PITIA.
Monthly rent −10%; expenses unchanged
1.13DSCR
-$250.00 / month change in rent minus PITIA.
Annual taxes +20% and insurance +20%; rent unchanged
1.20DSCR
-$85.00 / month change in rent minus PITIA.
Rent minus PITIA is not net profit: maintenance, vacancy reserves, management and other operating costs are excluded. These are educational estimates, not an approval, guaranteed rate or loan offer.
Includes every input and all three results. No account or contact details required; downloading sends nothing to a lender.
We’ll email your numbers and next-step questions, then review whether a lender option fits. If it does, we’ll ask before introducing you. A match, quote, or approval is not guaranteed.
Free email summary · phone optional · no credit check by this form
You can submit without completing the calculator. We’ll ask for an approximate loan amount and mark the DSCR as not yet calculated.
Free worksheet
Use the cash-out calculator to compare base rent with a lower-rent case, then download the assumptions, results and questions for a lender in one CSV. No payment or contact details required.
Open the free comparison →Pro is not currently available for new purchases. This worksheet is a separate free tool.
These are the program criteria we track, as each lender publishes them. Nothing here has been screened against a deal yet. Edit the example assumptions and select the property state to see which programs fit your numbers — and note that credit, reserves, appraisal, title, documentation, and provider underwriting are never checked here.
Screen these against your deal ↑Wide DSCR box that will look at ratios as low as 0.75 with compensating factors; a good backstop for marginal deals that other lenders decline.
Source: griffinfunding.com · read 2026-09-18
Tech-forward lender with a 30-year fixed DSCR product from a 0.75 ratio — one of the lowest floors here — plus an explicit short-term-rental program and instant online pricing.
Source: newsilver.com · read 2026-08-18
Visit New Silver via tracked link →High-volume tech-forward lender with fast DSCR closings and a no-income-doc 30-year product; competitive on A/B-class single-family and 2-4 unit. Its rental-loan page states that DSCR loans are originated and funded by Figure Lending LLC dba Figure as of 2026-09-01.
Source: kiavi.com · read 2026-06-15
Investor-only lender with an explicit short-term-rental DSCR program and a no-ratio option; strong fit for Airbnb deals where long-term rent is thin.
Source: easystreetcap.com · read 2026-06-15
Established private lender with a 30-year DSCR rental product from a 1.0 ratio and 660 FICO; up to 80% LTV on purchase plus a dedicated Airbnb/short-term-rental program (700 FICO, 1.3 DSCR).
Source: limaone.com · read 2026-09-18
Non-QM lender with flexible DSCR overlays including sub-1.0 'no-ratio' files; useful when the property does not cover PITIA but the borrower is strong.
Source: angeloakms.com · read 2026-06-15
Large retail lender with a DSCR investor line; steadier on long-term single-family rentals than on STR, with a conservative LTV ceiling.
Source: newamericanfunding.com · read 2026-06-15
One of the original DSCR shops; rate/term and cash-out refis on stabilized rentals with a clean, ratio-driven underwrite and a public DSCR calculator.
Source: visiolending.com · read 2026-06-15
Compensation disclosure: DSCRDealCheck may receive payment for partner-link activity, submitted inquiries, accepted leads, or completed loans. Compensation may affect which providers are included or displayed; it does not change the calculator math. Provider underwriting and terms control.
This is an educational estimate, not a loan offer, pre-approval, or commitment to lend. Providers determine rates, terms, eligibility, transaction classification, and applicable requirements. Not financial, legal, or tax advice.
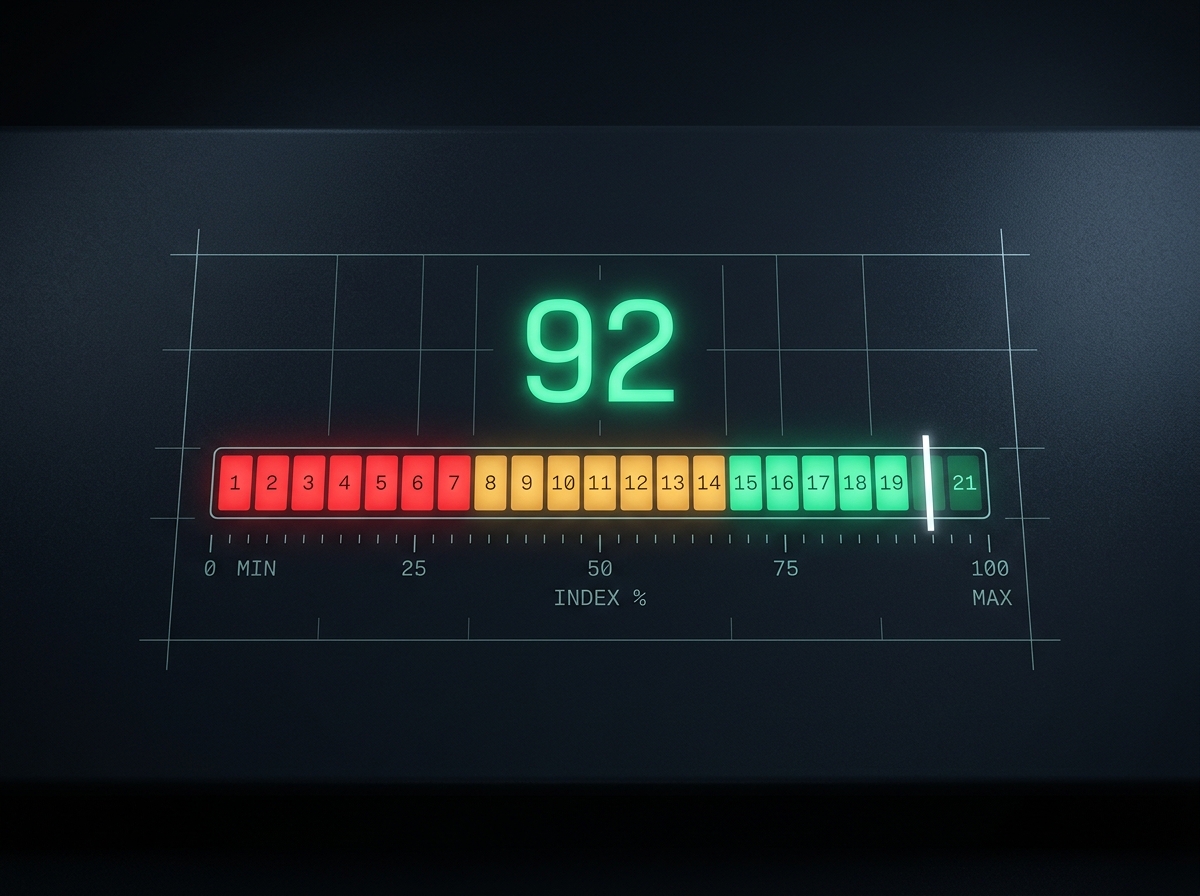
The meter uses the same displayed inputs and formula throughout: gross monthly rent divided by estimated PITIA.
Program information is presented as an indicative range, never as a personalized rate quote or commitment.
Program cards compare only the listed DSCR, loan-size, state, and property-type criteria. Provider underwriting controls.
Lender match
Once your deal is modeled, we compare its estimated DSCR, loan size, selected state, and property type with criteria in our program directory. The result is not underwriting, an approval, or a personalized rate quote. Any compensation relationship is disclosed separately.
Choose your financing moment
General DSCR math is only the first step. These guides help organize a transaction that is already moving toward a purchase, refinance, or written provider comparison.
Each guide includes the calculator, a scenario-specific checklist, questions to ask a provider, and primary sources. No contact details are required to use them.
Test whether stabilized value and rent can support the planned bridge takeout.
Stress-test the refinance exit after buying, renovating, and renting a property.
Reconcile down payment, points, costs, prepaids, deposits, and written credits.
Estimate the post-refinance payment before requesting proceeds and terms.
Organize the deal, property, entity, and timing details a provider will ask for.
Check the provider-specific questions that matter when the owner is outside the U.S.
Normalize rate, points, lender fees, prepayment terms, and cash to close.
DSCR Deal Lab
Three transparent financing teardowns show the inputs, arithmetic, and constraint behind a rent-stress result, a cash-to-close surprise, and a bridge-payoff gap.
Programmatic coverage
FAQ
A DSCR (debt service coverage ratio) loan is commonly used for non-owner-occupied investment property. Providers generally compare the property's rental income with PITIA (principal, interest, taxes, insurance, and HOA), while also applying their own credit, reserve, property, and documentation rules.
Use the calculator to estimate where the property's rent falls relative to PITIA. A ratio of 1.00 means estimated rent equals estimated PITIA, and 1.25 provides more coverage. The ratio alone does not determine eligibility; each provider performs its own underwriting.
Many DSCR programs do not use personal W-2 income or tax returns as the primary qualification test. Providers can still require credit, reserves, identity, entity, lease, appraisal, insurance, and other documentation.
Published program thresholds often begin around 1.00, with some providers advertising different treatment above 1.20 or 1.25. Minimum ratios, pricing, compensating factors, and no-ratio options vary by provider and can change.
DSCR programs are commonly intended for non-owner-occupied, business-purpose investment financing. The legal classification and laws that apply depend on the facts of the transaction and the provider's determination. DSCRDealCheck does not make that legal determination.


